Complete Guide to Marine Corps Pay and Benefits
Marine compensation is easy to flatten into one number and get wrong. The real value of service comes from five separate buckets working together: base pay, allowances, healthcare, education, and long-term structure. Anyone who compares one military base-pay number to one civilian salary misses most of what the package is worth.
- Marine Pay Guide How base pay, allowances, and total compensation actually work in 2026.
- Marine BAH Guide Housing allowance by pay grade, location, and dependency status.
- Marine GI Bill Guide Post-9/11 GI Bill coverage, housing allowance, and book stipend.
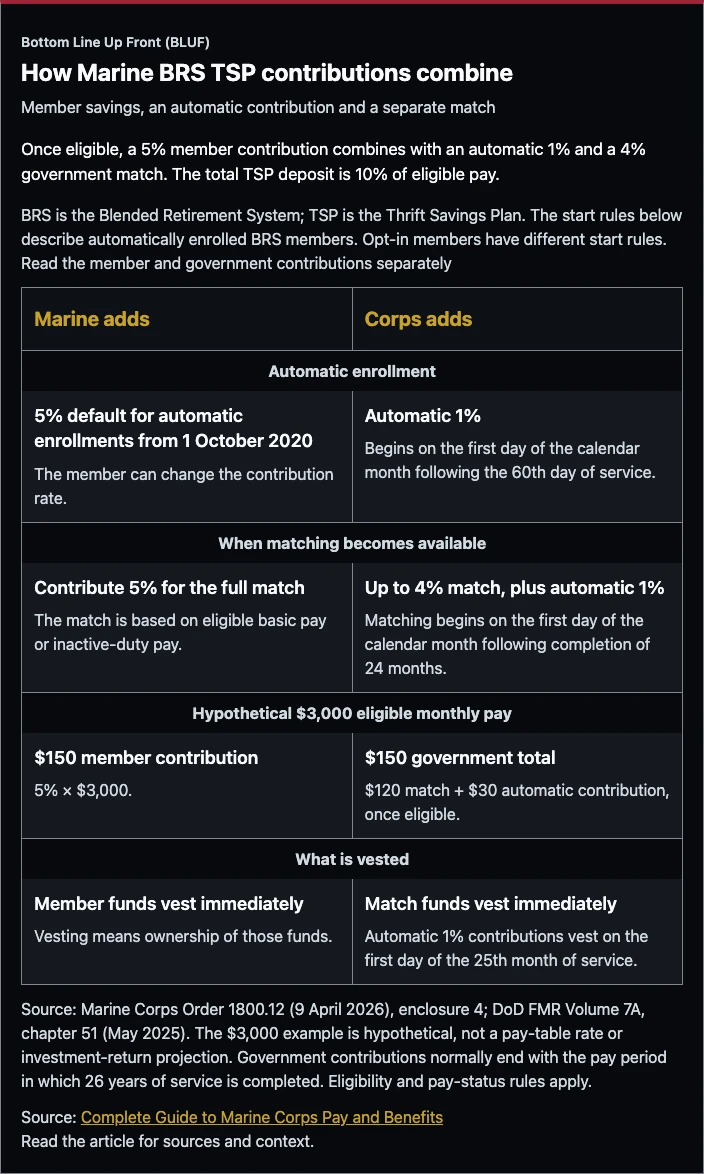
Once eligible, a 5% member contribution combines with an automatic 1% and a 4% government match. The total TSP deposit is 10% of eligible pay.
BRS is the Blended Retirement System; TSP is the Thrift Savings Plan. The start rules below describe automatically enrolled BRS members. Opt-in members have different start rules.
| Marine adds | Corps adds |
|---|---|
| Automatic enrollment | |
| 5% default for automatic enrollments from 1 October 2020The member can change the contribution rate. | Automatic 1%Begins on the first day of the calendar month following the 60th day of service. |
| When matching becomes available | |
| Contribute 5% for the full matchThe match is based on eligible basic pay or inactive-duty pay. | Up to 4% match, plus automatic 1%Matching begins on the first day of the calendar month following completion of 24 months. |
| Hypothetical $3,000 eligible monthly pay | |
| $150 member contribution5% × $3,000. | $150 government total$120 match + $30 automatic contribution, once eligible. |
| What is vested | |
| Member funds vest immediatelyVesting means ownership of those funds. | Match funds vest immediatelyAutomatic 1% contributions vest on the first day of the 25th month of service. |
Source: Marine Corps Order 1800.12 (9 April 2026), enclosure 4; DoD FMR Volume 7A, chapter 51 (May 2025). The $3,000 example is hypothetical, not a pay-table rate or investment-return projection. Government contributions normally end with the pay period in which 26 years of service is completed. Eligibility and pay-status rules apply.
Source: Complete Guide to Marine Corps Pay and Benefits
Read the article for sources and context.
On this page
The five layers of Marine compensation
Every comparison to civilian pay should start with this framework:
| Layer | What it covers | Why it matters |
|---|---|---|
| Base pay | Grade and years of service | The foundation, but not the ceiling |
| Allowances | BAS and BAH | Tax-free additions that change total take-home |
| Healthcare | TRICARE coverage | Replaces costs civilians pay separately |
| Education | GI Bill and Tuition Assistance | Long-term earning power that compounds after service |
| Long-term structure | Leave, retirement, and BRS | Benefits that build regardless of how the rest of the market moves |
Skipping any of those produces a bad comparison.
Base pay: the floor, not the ceiling
Base pay is set by grade (rank) and cumulative years of service. Every Marine at the same grade and years-in-service earns the same base pay regardless of MOS or duty station. The pay table is the same for everyone at a given point.
2026 enlisted base pay at common entry grades:
| Grade | Years of service | Monthly base pay |
|---|---|---|
| E-1 | Under 4 months | $2,225.70 |
| E-1 | Under 2 years | $2,407.20 |
| E-2 | Under 2 years | $2,697.90 |
| E-3 | Under 2 years | $2,836.80 |
| E-4 | Under 2 years | $3,142.20 |
| E-5 | Under 2 years | $3,342.90 |
| E-6 | Under 2 years | $3,401.10 |
| E-7 | Under 2 years | $3,932.10 |
2026 officer base pay at common entry grades:
| Grade | Years of service | Monthly base pay |
|---|---|---|
| O-1 | Under 2 years | $4,150.20 |
| O-2 | Under 2 years | $4,782.00 |
| O-3 | Under 2 years | $5,534.10 |
| O-4 | Under 2 years | $6,294.60 |
These are base pay only. They do not include allowances, special pays, or bonuses.
Pay progression changes the picture. An E-4 at 6 years earns $3,815.40 per month, meaningfully more than the $3,142.20 entry rate. An O-3 at over 4 years earns $7,382.70. For Marines who stay in and advance, the slope is steady.
BAS: the food allowance
Basic Allowance for Subsistence (BAS) is the monthly food allowance every eligible active-duty Marine receives. It does not vary by location.
Current 2026 BAS rates:
- Enlisted BAS:
$476.95per month - Officer BAS:
$328.48per month
BAS is not counted as taxable income. A civilian earning comparable base pay covers food from gross income before taxes. A Marine’s BAS sits outside that calculation.
One structural note: enlisted BAS is higher than officer BAS. The policy rationale differs by track. Officers are expected to cover more of their own meal costs in more situations. The BAS gap partially reflects that difference without negating the larger base-pay gap between the two tracks.
BAH: the housing allowance that changes the most
Basic Allowance for Housing (BAH) is the allowance that shifts total compensation most between assignments, because it varies by duty-station location, grade, and dependency status.
The core mechanics:
- Higher-cost metro areas produce higher BAH rates
- Marines with dependents receive a higher rate than single Marines at the same grade
- BAH is scaled to cover rental housing in the local market at the relevant grade’s rate
- BAH is not taxed as income
A Marine stationed in the Washington DC metro, San Diego, or Hawaii typically receives significantly more BAH than a Marine at an inland installation. At the same grade, the housing allowance difference between a high-cost and a mid-cost station can run several hundred dollars per month.
The Marine BAH Guide covers the full structure and links to the official DoD BAH lookup tool where you can check current rates by zip code and grade.
The practical point: a civilian peer earning the same dollar amount in base pay covers rent from gross income before taxes. Most active-duty Marines receive a tax-free housing payment that covers a substantial portion of rental costs in their duty-station market.
TRICARE: healthcare built into the package
Active-duty Marines receive TRICARE coverage as part of service, with a structure that most civilians their age cannot match on the open market.
Active-duty TRICARE Prime key facts:
| Item | Active-duty rate |
|---|---|
| Enrollment fee | $0 |
| Deductible | $0 |
| Copay at military treatment facilities | $0 |
| Family catastrophic cap (Group A) | $1,000 per year |
The catastrophic cap is the most important figure in comparison shopping. A Marine family with several dependents can access unlimited medical visits, hospitalizations, and treatments with a maximum annual out-of-pocket exposure of $1,000. A civilian family in a comparable income bracket might spend three to five times that in premiums alone, before any deductible or copay applies.
Healthcare is one of the most expensive benefits civilians buy separately. The Marine TRICARE Guide covers the full active-duty coverage structure and what changes when a Marine leaves active duty or moves to reserve status.
The GI Bill: education value that extends beyond service
The Post-9/11 GI Bill is one of the strongest education benefits available to any American worker. Marines who qualify carry a benefit that can fund significant post-service education at minimal personal cost.
Key GI Bill figures for AY 2025-2026:
| Component | Current value |
|---|---|
| Public in-state tuition | Covered in full |
| Private school annual tuition cap | $30,908.34 |
| Housing allowance (in-person student) | E-5 with dependents BAH rate at school zip code |
| Housing allowance (online-only student) | $1,169.00 per month |
| Books and supplies stipend | Up to $1,000 per year |
| Total benefit months | 36 |
The housing allowance for in-person students is based on the E-5 with dependents BAH rate for the school’s zip code. In higher-cost college towns that figure runs materially above the flat $1,169.00 online-only cap.
Transferability: Marines with at least 6 years of service can transfer unused GI Bill benefits to a spouse or dependent children in exchange for a 4-year additional service commitment. Children may use transferred benefits until age 26.
The practical point: a Marine who uses the full 36 months at a public in-state university pays essentially nothing for tuition and receives a monthly housing payment during school. Education value of that scale can easily outrun smaller monthly pay comparisons when measured over the full horizon.
The Marine GI Bill Guide covers the full program structure and how to calculate housing allowance by school.
Tuition Assistance: education while still serving
Tuition Assistance (TA) lets active-duty Marines take college courses before touching the GI Bill.
Current TA limits:
- Annual cap:
$4,500per fiscal year - Per-semester-hour cap:
$250 - Per-quarter-hour cap:
$166.67
TA preserves GI Bill eligibility. A Marine who completes a bachelor’s degree using TA over a 4-year enlistment can leave service with a degree paid for, GI Bill fully intact, and 36 months of education benefit available for graduate school or transfer to a dependent.
The combination, use TA during active duty for undergraduate work and hold GI Bill for post-service, is one of the cleanest long-term education-planning moves available.
Leave: 30 paid days every year
Active-duty Marines earn 30 days of paid leave per year, accruing at 2.5 days per month. Maximum carryover is 60 days.
In dollar terms, 30 days of leave is roughly one month of base pay held in reserve each year. An E-4 earning $3,142.20 in base pay accrues leave worth approximately that amount annually.
Most entry-level civilian jobs in the United States start at 10 to 15 days of paid time off. The military leave structure starts at 30.
The Blended Retirement System
The Blended Retirement System (BRS) combines a pension for Marines who qualify for retirement with retirement savings in the Thrift Savings Plan (TSP). Marines who first entered military service on or after January 1, 2018 are covered by BRS. Earlier entrants may be covered if they made an eligible election into it.
Having a TSP account alone does not establish BRS membership: Marines in a legacy retirement plan can contribute their own money to TSP without receiving BRS government contributions. See MCO 1800.12, enclosures 2–4 and the DoD Financial Management Regulation, Volume 7A, Chapter 51.
For a regular BRS retirement, the pension formula is 2% × creditable years of service × the average of the highest 36 months of basic pay. Twenty creditable years produce a 40% multiplier. Allowances and bonuses do not enter that basic-pay average.
Reserve retirement has a different calculation: qualifying years establish eligibility, while retirement points divided by 360 determine the years used in the pension multiplier. Twenty qualifying Reserve years do not automatically produce a 40% pension. MCO 1800.12, enclosure 6 explains the distinction.
For automatically enrolled BRS Marines, the current default member contribution is 5% of basic or inactive-duty pay; the 5% default applies to automatic enrollments from October 1, 2020. Marines can change their contribution. Without an investment election, contributions go into an age-appropriate Lifecycle fund.
| TSP feature | Rule for automatically enrolled BRS Marines |
|---|---|
| Member deduction and government automatic 1% | Begin the first calendar month after the 60th day of service |
| Government matching | Begins the first calendar month after completing 24 months of service |
| Full government contribution | A 5% member contribution earns a 4% match plus the automatic 1% once eligible |
| Ownership, called vesting | Member contributions and matching contributions vest immediately; the automatic 1% vests on the first day of the 25th month |
| Government contribution end | Automatic and matching contributions end after the pay period in which the Marine completes 26 years of service |
These dates use the Marine’s Pay Entry Base Date (PEBD). Earlier entrants who elected BRS have different contribution-start rules tied to their election; they do not start a fresh 24-month waiting period when opting in.
The automatic 1% does not require a member contribution, but receiving the full match requires contributing 5% of qualifying pay. MCO 1800.12, enclosure 4 provides the contribution and vesting rules.
Hypothetical monthly example: once fully eligible for matching, a Marine with $3,000 in monthly basic pay who consistently contributes 5% puts in $150. The government adds $30 automatically and $120 in matching contributions, for $300 total that month. This assumes qualifying pay and consistent contributions; $3,000 is an illustration, not a pay-table rate or a prediction of a future account balance.
BRS also includes continuation pay for eligible Marines at the 12-year PEBD milestone in exchange for four more years in the required component. The election must be signed and witnessed before reaching 12 years. For eligible Marines completing 12 years in calendar year 2026, the multiplier is 5.0 for Active Component and Active Reserve Marines, and 1.0 for eligible other Reserve Component Marines.
It is applied to monthly basic pay at the Marine’s current grade and over-12-years rate; the Reserve calculation uses the active-duty-equivalent rate. These are the 2026 component terms, subject to the eligibility and obligation rules in MCO 1800.12, enclosure 5.
The four-year continuation-pay obligation begins at the 12-year service anniversary and generally runs concurrently with other obligations unless those obligations preclude it. Marines with separation orders are not eligible, and some component changes or failure to complete the obligation can require repayment. A qualifying Marine may elect one payment or up to four equal annual installments under the order’s payment rules.
The Marine Retirement Guide explains the pension, TSP and continuation-pay pieces in more detail.
Special and incentive pays
Base pay and allowances do not capture every compensation element. Special and incentive pays apply in specific assignment contexts.
| Category | Examples |
|---|---|
| Aviation | Aviation Incentive Pay for qualifying aviators |
| Hazardous duty | Parachute duty pay, explosive ordnance disposal pay |
| Hostile fire or imminent danger | Applies in designated areas |
| Assignment-specific | Varies by tour, duty location, and career field |
| Enlistment and reenlistment bonuses | Tied to program categories and current recruiting needs |
These pays supplement base pay and allowances. Most Marines will not receive all of them. For specific communities, including aviation officers, cleared technical specialists, and certain warrant officer roles, specialty pay can add meaningfully to monthly compensation.
What builds after service
Service creates several durable benefits that continue after the uniform comes off.
VA Home Loan: Eligible veterans can purchase a primary residence with no down payment required on qualifying loans. The VA loan benefit does not expire and can be reused.
GI Bill (remaining entitlement): Unused GI Bill months remain available after separation. A Marine who used TA during service may leave with most or all of the 36-month education benefit still available.
VA Disability: Marines with service-connected conditions can receive VA disability compensation after separation. Ratings are independent of time in service (within honorable conditions) and have no income ceiling.
Veteran preference in federal hiring: Most federal agencies give veterans preference in competitive hiring. For cleared technical and analytical roles, a Marine Corps background can open direct pathways that civilian applicants cannot access.
The full comparison
A simple scenario: a civilian earning $60,000 per year versus an E-4 with under 2 years of service.
The civilian’s gross monthly income is $5,000.
The E-4’s monthly picture:
- Base pay:
$3,142.20 - BAS:
$476.95(tax-free) - BAH at a mid-cost installation: variable, often
$1,200to$2,000+(tax-free) - Healthcare: included, maximum family exposure
$1,000per year - TSP government contributions depend on BRS eligibility, service time and the member’s contribution; the full-match example above assumes matching eligibility
- Leave: 30 paid days annually
- GI Bill: 36 months of future education value building
Once BAH is included, the E-4’s total monthly cash compensation often exceeds $5,000 at a mid-to-high-cost station. When healthcare and education value are added to the comparison, the gap with a $60,000 civilian salary can close further or disappear depending on where the Marine is stationed and how they plan to use education benefits.
The honest version of this comparison: some civilian fields, particularly technology and finance at higher experience levels, will outpace the full military package. Military compensation is competitive because of the full package, not because base pay is high. The right answer depends on the specific civilian alternative, not a generic rule.
For the detailed benefit guides, go to the Marine Pay Guide for base pay and allowances, Marine TRICARE Guide for healthcare, Marine GI Bill Guide for education, and Marine Retirement Guide for the long-term picture. For the officer-versus-enlisted question, read Marine Officer vs Enlisted Pay Comparison.
- Marine TRICARE Guide Active-duty and family healthcare coverage explained.
- Marine Retirement Guide BRS pension, TSP matching, and long-term retirement planning.
- Complete Marine Pay Guide All five compensation layers covered in one place.