Marine Retirement: BRS Pension Calculator and Timeline
A Marine retirement calculator is useful only when its inputs match the member’s recorded retirement plan and service path. Twenty qualifying Reserve years don’t produce the same pension calculation as 20 creditable active-service years. The examples below separate eligibility, pension amount, TSP savings and payment timing so you can check what an estimate actually represents.
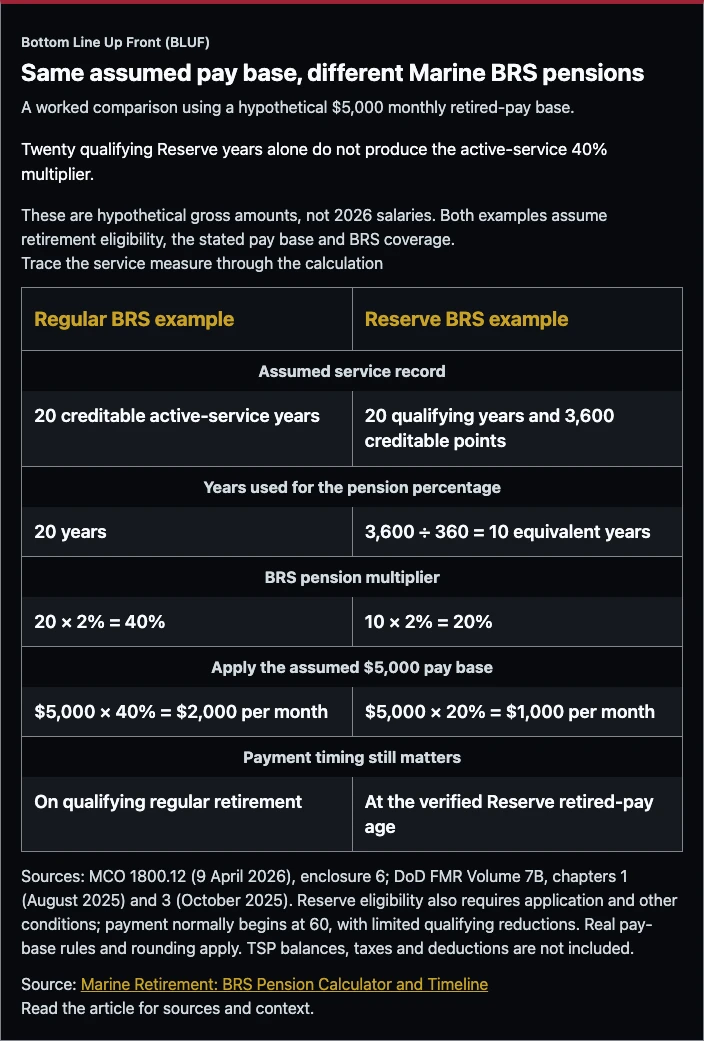
Twenty qualifying Reserve years alone do not produce the active-service 40% multiplier.
These are hypothetical gross amounts, not 2026 salaries. Both examples assume retirement eligibility, the stated pay base and BRS coverage.
| Regular BRS example | Reserve BRS example |
|---|---|
| Assumed service record | |
| 20 creditable active-service years | 20 qualifying years and 3,600 creditable points |
| Years used for the pension percentage | |
| 20 years | 3,600 ÷ 360 = 10 equivalent years |
| BRS pension multiplier | |
| 20 × 2% = 40% | 10 × 2% = 20% |
| Apply the assumed $5,000 pay base | |
| $5,000 × 40% = $2,000 per month | $5,000 × 20% = $1,000 per month |
| Payment timing still matters | |
| On qualifying regular retirement | At the verified Reserve retired-pay age |
Sources: MCO 1800.12 (9 April 2026), enclosure 6; DoD FMR Volume 7B, chapters 1 (August 2025) and 3 (October 2025). Reserve eligibility also requires application and other conditions; payment normally begins at 60, with limited qualifying reductions. Real pay-base rules and rounding apply. TSP balances, taxes and deductions are not included.
Source: Marine Retirement: BRS Pension Calculator and Timeline
Read the article for sources and context.
On this page
Choose the retirement path before entering numbers
A Marine retirement scenario starts with two decisions about the calculation: which retirement system applies, and whether the scenario is regular active-duty retirement or non-regular Reserve retirement. Those choices determine the multiplier, service measure, and payment timeline. Changing a salary field cannot correct a scenario built for the wrong retirement path.
Marines with a Date Entered Armed Forces on or after January 1, 2018, are automatically covered by the Blended Retirement System (BRS). Earlier entrants generally remained in a legacy plan unless they made an eligible BRS election, including under the specific extension provisions. The Marine Corps BRS order explains those enrollment rules.
Don’t select High-3 simply because a Marine entered before 2018. Legacy retirement includes Final Pay and Career Status Bonus/REDUX as well as High-3, and those plans aren’t identical. Confirm the plan in the service record before comparing projected benefits.
This page explains planning arithmetic; it doesn’t contain an interactive retirement calculator. The site’s Marine Corps pay calculator estimates supported active-duty recurring pay, including selected allowances, rather than retirement income. It doesn’t calculate a high-36 history, Reserve points, a TSP balance, or a BRS lump-sum offer.
For a broader explanation of each benefit, use the Marine Retirement and BRS Guide. Here, the task is narrower: build a scenario whose inputs mean what the calculation assumes they mean. A useful estimate should let you trace every dollar back to an assumption or a record.
Keep four different inputs separate
Service time: which clock is being used?
For a regular BRS pension, the service multiplier is 2% for each creditable year, with full additional months recognized under the applicable rules. Twenty creditable years therefore produce a 40% multiplier. Standard High-3 uses 2.5%, producing 50% at 20 years, but REDUX requires different treatment.
The continuation-pay clock is measured from the Pay Entry Base Date, while retirement eligibility and pension-computation service must be checked under their own rules. A date entered into one field shouldn’t silently stand in for every service measure. If a Marine has prior service or a break in service, ask the administrative section to identify the correct dates and credited periods.
Points: eligibility and percentage aren’t the same
For non-regular Reserve retirement, qualifying years and the point total perform separate jobs. A qualifying year generally requires at least 50 points, while the usual service threshold is 20 qualifying years, subject to the other eligibility conditions. The pension percentage is calculated from total creditable points divided by 360, then multiplied by the applicable retirement-system percentage.
A Reserve scenario that substitutes 20 qualifying years directly into the active-duty BRS formula would produce 40% without establishing the correct point-based multiplier. Check the annual qualifying-year history and the total points as separate inputs. Both appear in the planning file because neither proves the other.
Pay base: an average isn’t the latest salary
The high-36 calculation generally uses the highest 36 months of basic pay, rather than one month’s pay at the final grade. It doesn’t turn a housing allowance into pensionable basic pay. A promotion during the averaging period also doesn’t retroactively increase the earlier months.
Reserve pay-base rules need additional care. Volume 7B, Chapter 3 of the DoD Financial Management Regulation distinguishes members awaiting retired pay from former members discharged to civilian status. That distinction can change which months are available for the high-36 calculation, even when two scenarios begin with the same retirement point total.
Payment age: when does the income become available?
Regular retirement and non-regular retirement don’t have the same payment schedule. A qualifying regular retiree generally begins retired pay with retirement, while non-regular retired pay normally begins at age 60 after the applicable requirements and application are met. Finishing the required Reserve qualifying years doesn’t automatically start a monthly pension.
Qualifying active service may reduce the Reserve payment age by three months for each aggregate of 90 eligible days, within the permitted fiscal-year grouping rules and no earlier than age 50. This isn’t a rule requiring 90 consecutive days, and not all active-duty orders qualify. Use an administrative determination supported by the orders rather than subtracting every deployment day from age 60.
Compare two pensions using one hypothetical pay base
Assume both examples have a $5,000 applicable monthly retired-pay base. This is a deliberately hypothetical input, not a 2026 salary or a promise that two real Marines would have the same high-36. Holding it constant makes the effect of the service measure visible.
| Assumption | Regular BRS example | Non-regular BRS example |
|---|---|---|
| Service used for percentage | 20 creditable years | 3,600 creditable points ÷ 360 = 10 equivalent years |
| BRS multiplier | 20 × 2% = 40% | 10 × 2% = 20% |
| Assumed monthly pay base | $5,000 | $5,000 |
| Gross monthly pension | $2,000 | $1,000 |
| Payment timing | On qualifying regular retirement | At the verified non-regular payment age |
The Reserve example also assumes the member has met the qualifying-year requirement and all other conditions for non-regular retired pay. Having 3,600 points alone doesn’t establish that every required year qualified. The example uses a point total divisible by 360 so rounding doesn’t obscure the comparison.
For the regular scenario, two more full creditable years would raise the BRS multiplier from 40% to 44%. If the hypothetical pay base stayed at $5,000, that change alone would raise gross monthly retired pay from $2,000 to $2,200. A real estimate should separately account for any change in the high-36 average rather than attributing the entire increase to extra service.
For the Reserve scenario, adding creditable points changes the percentage calculation, while eligible orders may separately affect payment age. Those are two different changes to record. An estimate that shows a higher pension but omits years of waiting before payment gives an incomplete cash-flow picture.
The same $5,000 base and 20 creditable years under standard High-3 would produce $2,500 gross monthly retired pay. That doesn’t establish which system produces greater total wealth, because it excludes TSP contributions, investment results, and personal circumstances. It also doesn’t apply the REDUX adjustments or special retirement rules.
Put the pension and TSP on separate lines
A pension estimate is recurring gross income under a defined-benefit formula. A TSP statement is an account balance, and money available from that account depends on applicable distribution rules and the choices made. Adding the entire account balance to one year’s pension creates a total with mismatched units.
A clearer planning sheet has a pension-income line, a TSP-balance line, and a separate line for any assumed TSP distributions. Label distribution assumptions rather than presenting them as benefits guaranteed by the pension formula. This also makes it easier to see a period when a Reserve Marine has stopped drilling but hasn’t reached retired-pay age.
Legacy Marines can contribute their own money to TSP; the absence of BRS matching doesn’t exclude them from the account. Under BRS, the government contributes a separate automatic 1% and, once matching eligibility begins, up to another 4% in matching contributions. A Marine contributing 5% of eligible pay can therefore receive a total government contribution of 5%, subject to the applicable rules and limits.
For automatically enrolled BRS entrants, the government automatic contribution begins after the first 60 days under the Marine Corps timing rules, while matching starts after completion of 24 months. Eligible opt-in members have different contribution start rules tied to their election. A projection should therefore avoid assuming every entrant received the maximum match from the first paycheck.
New BRS accessions on or after October 1, 2020, are automatically enrolled at a 5% member contribution rate after the initial service period. That deduction comes from the Marine’s pay, and the Marine may change it. Check the actual Leave and Earnings Statement rather than assuming a Marine who never selected a percentage has contributed nothing.
Ownership also differs by contribution type. Member contributions and government matching are immediately vested when received in TSP, while the government automatic 1% vests on the first day of the 25th month of service. Government automatic and matching contributions normally end with the pay period in which 26 years of service is completed.
Newly enrolled BRS members generally default to an age-appropriate Lifecycle fund, with existing elections and reentry circumstances requiring an account check. A default allocation doesn’t establish a future return or choose an investment strategy for a particular household. Use the actual account balance as the starting point and keep any projection assumptions visible.
Build the continuation-pay decision around the 12-year date
The Marine Corps’ continuation-pay milestone under its current BRS order is 12 years of service measured from the Pay Entry Base Date. Eligible Marines accept four additional years of obligated service, beginning on the 12-year anniversary. A generic eight-to-twelve-year description of the wider BRS framework doesn’t identify the Marine Corps’ actual election requirements.
For eligible Marines reaching 12 years during calendar year 2026, MARADMIN 003/26 specifies a 5.0 multiplier for the active component and Active Reserve. Eligible Reserve-component Marines not serving in the Active Reserve use 1.0. Apply those annual terms only to the cohort the notice covers.
The calculation uses the Marine’s current grade and the over-12-years monthly basic-pay rate. For a non-Active-Reserve member, the reference is basic pay as if on active duty, rather than drill pay. With a hypothetical applicable rate of $5,000, those multipliers would produce gross payments of $25,000 and $5,000 respectively.
A planning timeline should place the election before the anniversary, followed by the service obligation beginning at that milestone. The order excludes participants whose statements of understanding are signed or witnessed on or after reaching 12 years. Complete the required financial-awareness preparation and verify the unit’s processing steps early enough to resolve a record or eligibility problem.
The commitment generally runs concurrently with other obligations unless another obligation prevents it. The required component or duty status matters, and some transfers or failure to complete the agreement can trigger repayment. A larger retirement projection cannot decide whether that service agreement fits the Marine’s circumstances.
The payment can be received at once or in up to four equal annual installments. Keep the gross amount, withholding, and actual payment dates separate in the cash-flow scenario. Don’t treat an installment choice as permission to shorten the four-year obligation.
Model the lump sum as a trade in payment timing
The BRS lump-sum option exchanges part of the monthly pension for an earlier discounted payment. Eligible members may elect the discounted present value of 25% or 50% of estimated gross retired pay during the defined window. The window ends at the restoration point tied to the member’s applicable Social Security full retirement age, generally 67 for most Marines.
Using the hypothetical $2,000 monthly pension, a 25% election illustrates a $500 monthly reduction, leaving $1,500 during the reduction period. A 50% election illustrates a $1,000 reduction, leaving $1,000. These figures explain the monthly trade; they don’t calculate the actual upfront payment, future adjustments, or taxes.
The lump-sum amount isn’t simply the reduction multiplied by every month until age 67. DoD applies a discount rate and projected cost-of-living adjustments, and the relevant window starts when retired pay becomes payable. That start date can be much later for a non-regular Reserve retirement than the date a Marine leaves paid Reserve service.
Full monthly retired pay is restored on the first day of the month following the month in which the applicable full retirement age is attained. The election is required no later than 90 days before the applicable regular-retirement or non-regular-pay eligibility date. Chapter 61 disability retirement isn’t eligible for this BRS election.
The Marine Corps annuity rules identify further interactions involving VA disability compensation, survivor coverage, taxes, and court orders. Bring the actual offer to a certified Personal Financial Manager before deciding. A scenario with an assumed investment return cannot establish that the lump sum is preferable for every retiree.
Turn the scenario into questions that records can answer
Save the estimate with its assumptions and a date, then take unresolved inputs to the office that can verify them. The unit administrative section can help establish the recorded retirement system, credited service, and continuation-pay anniversary. Reserve questions also need the qualifying-year statement, total points, and orders supporting any reduced payment age.
Check the TSP contribution history against payroll records and the account statement. If deductions or government contributions appear missing, ask about the cause: the DoD TSP rules include correction provisions for certain agency errors. A voluntary contribution choice and an administrative error aren’t the same planning event.
Use a Personal Financial Manager to discuss how the verified benefit dates fit the household’s expenses and other income. Keep the full Marine pay and benefits picture available for related questions, without importing every current allowance into the pension base. The useful output is a traceable scenario that can be revised when a record or career assumption changes.